
How to handle overdue financial commitments in the church without panic
How to handle overdue church financial commitments without panic: map debts, talk to the creditor, set payment priorities, communicate and prevent a repeat.
In this article
- Why church overdue payments get worse when they are hidden
- What the Bible says about debt and keeping your word
- Mapping the real situation: an inventory of church debts
- Talking to the creditor: a script for the first call
- A priority plan: what to pay first
- Transparent communication by church size
- Preventing it next time: choices and their costs
- Example: a church of 110 members with overdue bills
- This week, before the next bill falls due
- Mistakes that turn a late payment into a crisis
- Frequently asked questions
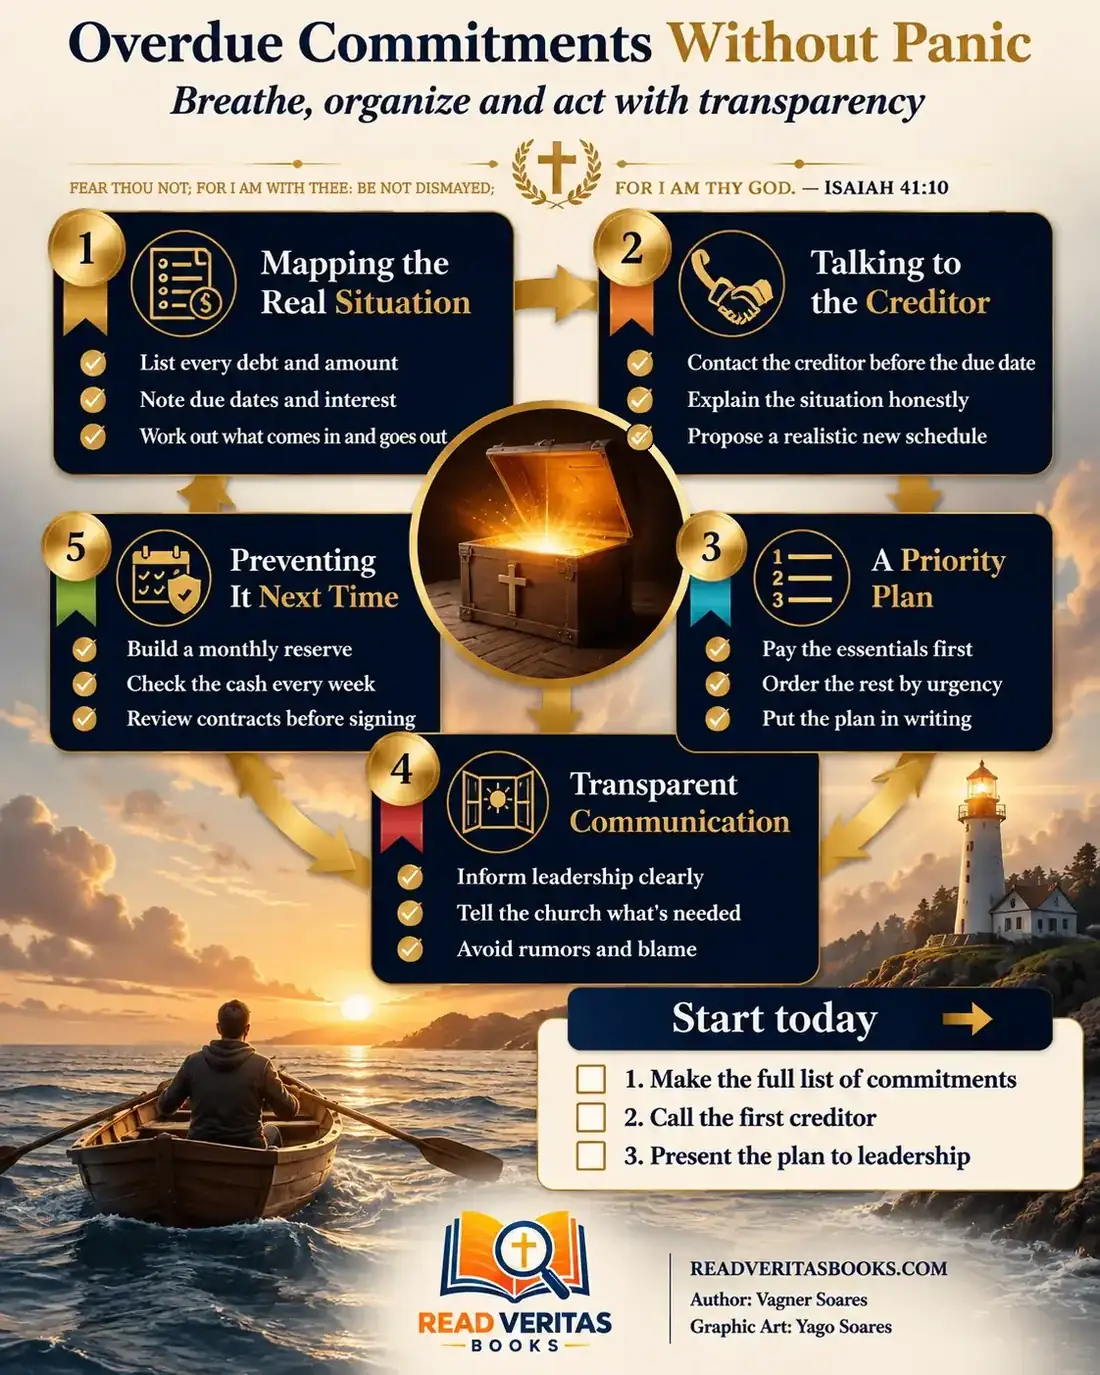
Free mind map
This whole guide on one page
The five steps in this article as an infographic you can print, pin on the notice board or send to your team.
There comes a month when giving drops, an important bill falls due and the cash doesn't stretch. The first reaction is often panic, silence or the temptation to hide the problem until it grows. The delay stops being just a money matter and begins to disturb the leaders' peace and the church's trust.
This guide proposes a calm, transparent path: map the real situation, talk with creditors, set priorities, communicate clearly and build safeguards for next time. When taxes, salaries or the risk of a lawsuit are involved, also consult an accountant and a lawyer where you are.
Fear thou not; for I am with thee: be not dismayed; for I am thy God.
Isaiah 41:10
Why church overdue payments get worse when they are hidden
A bill one week overdue is an administrative problem. The same bill four months overdue, with interest, a late fee and a creditor who no longer picks up the phone, becomes a church financial crisis. What separates the two is rarely the amount; it is how long the leaders took to face it.
When the treasurer carries the weight alone, they start making decisions that are not theirs to make: delaying one bill to pay another, asking someone for an advance, leaving an expense unrecorded. None of this comes from bad faith; it comes from fear. Acting early simply means putting the numbers on paper and gathering the right people.
Advertisement
What the Bible says about debt and keeping your word
The opening verse was spoken to Israel, called God's servant, in a time of threat. It does not promise that the bill will disappear; it promises presence. That changes the starting point: the leaders do not decide out of dread.
Psalm 37 is a wisdom psalm that teaches God's people not to fret over the prosperity of the wicked. In the middle of it, David draws a contrast: "The wicked borroweth, and payeth not again: but the righteous sheweth mercy, and giveth" (Psalm 37:21). The verse describes a character, someone who takes with no intention of repaying. It does not say that every church with an overdue bill is wicked, nor does it forbid all borrowing. It shows which side the church wants to be on: the side of those who seek to pay, even while asking for more time.
In Romans 13, after speaking about the governing authorities, Paul concludes: "Render therefore to all their dues" (Romans 13:7), and then, "Owe no man any thing, but to love one another" (Romans 13:8). The focus is not leaving obligations open, taxes included. Using the passage as a detailed rulebook on credit, or as an accusation against a church in crisis, goes beyond what Paul is discussing.
In 2 Corinthians 8, Paul organizes the collection for the poor believers in Jerusalem, and he does not handle the money alone: a brother chosen by the churches travels with him (2 Corinthians 8:19), "Providing for honest things, not only in the sight of the Lord, but also in the sight of men" (2 Corinthians 8:21). For anyone running a church with debts, a clear conscience before God is not enough; people need to be able to see what is being done.
Mapping the real situation: an inventory of church debts
"Be thou diligent to know the state of thy flocks" (Proverbs 27:23), the proverb tells the owner of a herd. What needs counting now is the church's commitments. A lot of anxiety comes from imagined numbers. Work in this order:
- Gather in one place the bank statements for the last six months, bills, invoices, contracts, payment reminders and the treasurer's notebook.
- Make a single list, one line per commitment, with the creditor, original amount, current amount with interest and fees, due date and status (overdue, due this month, up to date).
- Include the informal commitments: a loan from a member, goods bought on credit, an expense the pastor paid out of pocket.
- Work out the average income and fixed expenses over the last six months. A single month is misleading.
- Find the monthly gap. That number is the church's real capacity to pay, and it may be zero or negative.
- Summarize everything on one page: total overdue, total due in the next 60 days, monthly gap and the three most urgent bills.
Do this in pairs: the treasurer and one trusted person. That is protection, not suspicion.
Talking to the creditor: a script for the first call
Negotiating with creditors is almost always better than disappearing. Many would rather be paid on a new schedule than face a long process, and someone who calls first is seen very differently from someone who vanishes. Before you call, have the one-page summary in front of you and know what the church can pay each month.
A script you can adapt:
"Good morning, this is [name], [role] at [church name]. I'm calling before you have to chase us. The [month] payment of [amount] is overdue because our income has dropped and we are reorganizing all our bills. We are not trying to avoid paying. Right now we can pay [amount] a month. Would it be possible to split the overdue amount into [number] payments starting on [date]?"
Then confirm it in writing:
"Following our conversation today, [church name] will pay the overdue amount of [amount] in [number] payments of [amount], on the [day] of each month, starting on [date]. The regular contract payments will be [unchanged / paused until date]. Please confirm whether you agree."
Promise only what the monthly gap allows. Jesus' words, "let your communication be, Yea, yea; Nay, nay" (Matthew 5:37), apply to a payment arrangement too. Don't accept on the spot a proposal you haven't checked with the treasurer, and file the creditor's confirmation with the original contract.
Advertisement
A priority plan: what to pay first
When there isn't enough for everything, someone will decide the order. Better that it is the leaders, in writing, than whichever bill arrived last. Apply these rules from the top down:
- If the unpaid bill would cut off an essential service (electricity, water, rent on the place of worship), it comes before the others.
- If it involves salaries, payroll obligations or taxes, treat it as a priority and confirm the consequences with a local accountant, since they vary by country.
- If it charges high interest, such as a credit card or an overdraft, it moves ahead of debts that don't grow over time.
- If the creditor is a church member, don't push them to the back because "he's a brother, he'll understand." Agree on a deadline in writing and keep it.
- If a spending item can be paused without hurting anyone, pause it before letting another bill go overdue.
- If the only way out seems to be a new loan to cover the old ones, stop and talk to the accountant before signing anything.
Record the plan in the minutes, with the date and the next review already set. A written plan prevents competing versions and shows seriousness when anyone asks.
Transparent communication by church size
One rule applies to every church: the leaders first, with the full numbers; then the congregation, with what they need in plain language; never the names of individual creditors, individual salaries or donors' details. The format changes with size.
Small church (up to about 100 people)
News travels fast. Gather the pastor, treasurer and leaders in the same week the list is finished, then explain the situation at a members' meeting with a single page of totals. If one of the creditors belongs to the church, they must not be exposed.
Medium church
Present the map and the plan to the board before any public announcement. Tell ministry leaders what changes for them, such as frozen purchases. Only then give a short update at a service or a members' meeting.
Large church
The finance committee prepares a formal report and one person speaks for the leadership. Leaders receive the agreed answers in writing, so no one improvises in the messaging groups. To balance openness and privacy, see how to build financial transparency without exposing donors.
Preventing it next time: choices and their costs
Jesus asked "which of you, intending to build a tower, sitteth not down first, and counteth the cost" (Luke 14:28). He was talking about the cost of following him, not about budgets, but the image only works because counting the cost first was obvious wisdom to anyone listening.
Setting aside a fixed amount for a reserve each month means postponing some purchase. Even so, a reserve is what turns the next drop in giving into an adjustment rather than an overdue bill; see how to start a church reserve fund. Buying the sound system or the renovation on installments solves today and commits the months ahead: don't take on a new installment that doesn't fit the approved budget, and if there isn't one yet, start by building the church's annual budget.
Checking the cash every week shows the warning signs early, but it must not turn into exhausting surveillance. Fifteen minutes between treasurer and pastor is enough, with three numbers: balance, bills due in the next two weeks and income so far this month. And before signing any contract, read the deadlines, penalties and termination terms; a contract with no way out is a debt waiting for a crisis.
Example: a church of 110 members with overdue bills
Take a church of 110 members that saw giving fall after several families moved away. Average income settled at 18,000 a month and fixed expenses at 21,000. The treasurer kept juggling the bills alone until two electricity bills, one installment for the roof repair and one for the sound equipment were all overdue.
On Friday, he and the pastor built the list from the bank statements. A forgotten commitment surfaced: 6,000 lent by a deacon, with no agreed date. The total overdue came to 14,000, and the monthly gap was 3,000 in the red.
Following the priority rules, electricity was paid first from the account balance. On Monday, the pastor called the builder using the script and proposed splitting the overdue installment into three; the company confirmed by message. The sound equipment store agreed to pause two installments and extend the contract. The deacon agreed, in writing, to be repaid from the seventh month.
On Tuesday, the board approved in the minutes: purchases frozen for three months, the youth retreat postponed, a monthly review. On Sunday, the pastor spoke to the church for three minutes, showed the totals without names and explained what had already been negotiated. Four months later, the installments were up to date and the church began setting aside 500 a month for a reserve.
This week, before the next bill falls due
- Today, ask the treasurer for the statements and bills and book a time to build the list with a second person.
- By Wednesday, finish the one-page summary.
- On Thursday, call the creditor with the most urgent bill and send the written confirmation the same day.
- By Sunday, meet with the leaders, approve the priority plan and set the date of the first review.
Mistakes that turn a late payment into a crisis
- Waiting for the creditor to call. Whoever reaches out first negotiates on better terms.
- Agreeing to a plan the monthly gap can't support, then breaking it two months later.
- Asking for a special offering with a tone of spiritual urgency, without numbers or a plan. Generosity grows from clarity, not pressure.
- Going back to normal as soon as the cash recovers, without a reserve or a review of contracts.
Frequently asked questions
Can a church take out a loan to pay overdue debts?
Sometimes, for example to replace a high-interest debt with a cheaper one. It only makes sense if the new payment fits within the real monthly gap. Take the proposal to the accountant and the leaders before signing.
Should I ask members for help to pay a church debt?
It depends on the situation and the church's culture. If you do, make it clear, voluntary and transparent: how much is missing, what it will be used for and how the church will report back. Never pressure or expose anyone.
When should I seek an accountant or lawyer?
When the debt is large or involves taxes, salaries, complex contracts or the risk of a lawsuit. A local professional helps you understand obligations and rights, which vary by country and type of debt.
What if the church truly cannot pay?
Talk with each creditor about renegotiating, cut what isn't essential and consider with the leaders selling or using some asset. In serious situations, get legal advice before deciding.
A financial crisis handled with numbers on paper, honest conversations and a written plan usually passes faster than people expect. To prepare, see also how to make a plan for a drop in giving, build the church reserve fund and take care of contracts with vendors and service providers.

Vagner Soares is a presbyter with pastoral ordination, a mentor and a digital entrepreneur with more than 10 years of experience in technology, digital marketing and education.
Keep reading
 Financial planningConservative investing for the church's reserve: what to consider before decidingWhat to consider before investing the church's reserve: safety before returns, liquidity, simple options, who decides and signs, and a regular review.Read the article
 Financial planningDesignated funds (missions, building, children's): how to organize them without mixing the cashOrganize designated church funds, like missions, building and children's, without mixing the cash: separate accounts, entry records, donor reports and leftovers.Read the article
 Financial planning · Reference guideThe Complete Guide to Church Financial Management: Five Pillars That Hold the Books TogetherOrganize your church finances with a budget, transparency, a reserve, accountability, and a crisis plan. A practical guide for pastors and treasurers.Read the article